
What Are Current Mortgage Rates in Minnesota?
Rates change so often that by the time you read a number online, it might already be outdated. So how do you actually keep track of what you would pay right now. As of mid September 2026, 30 year fixed mortgage rates in Minnesota have been trending in the neighborhood of 7 percent, with 15 year fixed rates running roughly half a point to three quarters of a point lower. These numbers move daily based on broader economic conditions, so the only way to know your actual rate is to get a live quote from a lender when you are ready to move forward. Why Mortgage Rates Change So Often Mortgage rates are tied to the bond market, inflation data, decisions from the Federal Reserve, and overall investor demand for mortgage backed securities. None of those things stay still for long, which is why rates can shift meaningfully within the same week, and sometimes within the same day. The Difference Between the Rate You See Online and the Rate You Get The rates published on comparison websites are averages, often based on strong credit profiles and specific loan terms. Your actual rate depends on your credit score, down payment size, loan type, property type, and the specific lender you work with. Two buyers looking at the same house can be offered noticeably different rates based on their individual financial picture. Fixed Rate Versus Adjustable Rate in Today’s Environment A fixed rate mortgage keeps the same interest rate for the entire loan term, which offers predictability. An adjustable rate mortgage typically starts with a lower rate for an introductory period before adjusting based on market conditions. In a higher rate environment, some buyers explore adjustable options to lower their initial payment, but it is important to understand exactly how and when the rate can change before choosing that route. How Even Small Rate Differences Affect Your Payment A difference of even a quarter or half a percentage point on a mortgage rate can change your monthly payment by a meaningful amount over a 30 year loan, and it adds up even more over the life of the loan. This is why shopping rates between a few lenders, rather than accepting the first quote you receive, is worth the time it takes. What You Can Do to Get a Better Rate Improving your credit score before applying, saving for a larger down payment, reducing existing debt, and comparing offers from multiple lenders are the most direct ways to influence the rate you are offered. Some buyers also consider paying for mortgage points to lower their rate further, which can make sense depending on how long you plan to stay in the home. Where to Get an Accurate, Current Number Because rates shift daily, the most reliable way to know what you would actually pay is to request quotes from a few lenders once you are seriously preparing to buy. I work with trusted lenders across the Twin Cities and can help connect you with a few options so you can compare real, current numbers side by side instead of relying on a website average. Frequently Asked Questions Q: Are mortgage rates the same at every lender? A: No. Rates vary between lenders based on their own costs, risk models, and current pricing, which is why comparing multiple lenders matters. Q: Does my credit score really make a big difference in my rate? A: Yes, often a significant one. Buyers with stronger credit scores typically qualify for lower rates, while lower scores usually come with higher rates to offset the lender’s risk. Q: Should I wait for rates to drop before buying? A: That depends on your personal timeline and finances more than on trying to predict the market. Rates are unpredictable, and waiting has its own costs, including continued rent payments and potential home price increases. Q: What is a rate lock? A: A rate lock is an agreement with your lender to hold a specific interest rate for a set period while your loan is being processed, protecting you from rate increases during that window. Q: Can I negotiate my mortgage rate? A: To some extent, yes. Comparing offers from multiple lenders and asking whether they can match or beat a competing quote is a normal part of the process. Q: How often should I check current rates while I am house hunting? A: It is reasonable to check in periodically, but do not make yourself anxious over daily swings. Focus on getting a real quote once you are close to making an offer, since that is the number that actually matters. Closing Call to Action If you want help understanding what rate you might realistically qualify for, or you want an introduction to lenders who can give you a current, accurate quote, reach out to me and we will get you real numbers instead of guesses.
What Happens If the Home Inspection Finds Problems?
The inspector spends a few hours in the home you thought was perfect, and then hands you a report with more pages than you expected. Finding problems during a home inspection is normal, even in homes that show beautifully. What matters is what you do next. Depending on what was found and the terms of your purchase agreement, you can ask the seller to make repairs, request a credit or price reduction, or in some cases walk away from the deal entirely. Why an Inspection Report Almost Always Has Findings No home is perfect, including new construction. Inspectors are trained to note everything, from a genuinely serious structural concern down to a loose handrail or a light switch that needs a cover plate. A long report does not automatically mean the home is a bad buy. It means you now have detailed information to make a decision with, instead of guessing. How to Separate Minor Items From Major Ones The first step is sorting the findings by severity. Cosmetic items and simple maintenance fixes are usually not worth negotiating over. What deserves real attention are issues involving the roof, foundation, structural elements, major systems like heating and plumbing, electrical safety concerns, or signs of water intrusion. Your agent, and often the inspector themselves, can help you prioritize what actually matters. Your Options Once You Have the Report If you have an inspection contingency, you generally have a few paths. You can ask the seller to complete specific repairs before closing, request a credit at closing so you can handle repairs yourself after you own the home, ask for a reduced purchase price, or walk away from the deal if the issues are serious enough and the seller will not negotiate. Which option makes sense depends on the size of the issue and how much you want the home. How Sellers Typically Respond Sellers are not obligated to fix everything you ask for, and negotiations after an inspection can go back and forth much like the original offer did. Some sellers will agree to significant repairs to keep the deal together, others will offer a credit instead of doing the work themselves, and some will decline entirely if they feel your requests go beyond what is reasonable for the price already agreed upon. When Walking Away Makes Sense If the inspection reveals something that changes your entire view of the property, such as a failing furnace, significant foundation movement, or a roof that needs full replacement sooner than expected, and the seller will not negotiate a reasonable resolution, walking away is a legitimate option if your contingency allows it. It can feel disappointing after getting this far, but it is far better than closing on a home with problems you cannot afford to address. What Happens If You Do Nothing You are never required to act on every item in an inspection report. If the findings are minor and do not concern you, you can simply move forward with closing as planned. The report exists to inform your decision, not to force a negotiation you do not want to have. Frequently Asked Questions Q: Does every inspection find something wrong? A: Almost always, yes. The question is whether what is found is minor and expected or serious enough to warrant negotiation. Q: Can I ask for anything I want after an inspection? A: You can ask, but sellers are not required to agree. Reasonable requests tied to safety or major systems are more likely to be negotiated successfully than requests for cosmetic updates. Q: What if the seller refuses to fix anything? A: You can decide whether to accept the home as is, request a credit instead of repairs, or exercise your right to cancel if your contingency allows it and the issues are significant. Q: Should I get a specialist to look at something the inspector flagged? A: Yes, if the general inspector recommends further evaluation of something like the roof, foundation, or major mechanical systems, it is worth getting that specialist opinion before you negotiate or make a final decision. Q: Can I still buy the home if there are unresolved issues? A: Yes, some buyers choose to proceed knowing they will handle certain repairs themselves after closing, especially if the price already reflects the home’s condition. Q: How long do I have to respond after receiving the inspection report? A: Your purchase agreement will specify a deadline for the inspection period, so talk with your agent right away once you receive the report to make sure you respond in time. Closing Call to Action An inspection report full of findings can feel overwhelming at first glance, but you do not have to sort through it alone. If you want help interpreting a report or negotiating repairs, reach out to me and we will figure out the right next step together.
Can I Waive an Inspection in Minnesota?
In a competitive market, someone tells you waiving the inspection will make your offer stand out. Before you do that, it is worth understanding exactly what you would be giving up. Yes, you can legally waive a home inspection in Minnesota, and some buyers do it to make their offer more competitive. But waiving the inspection means you are accepting the home as is, with no ability to negotiate repairs or credits based on what an inspector might find, and no ability to walk away if a major issue turns up after closing. What Waiving an Inspection Actually Means Your purchase agreement can include an inspection contingency, which gives you a set number of days to have the home professionally inspected and the right to negotiate or cancel based on what is found. Waiving that contingency means you skip that protection entirely, or you might still get an inspection purely for your own information but give up the right to act on the results. Why Buyers Consider Waiving It In a market where a home receives multiple offers, an inspection contingency can make a buyer’s offer look less attractive to a seller because it introduces uncertainty about whether the deal will actually close. Some buyers waive the contingency, or shorten the inspection period significantly, hoping it will help their offer win out over others. What You Are Risking When You Waive It This is the part that deserves real thought. Homes can have issues that are not visible during a normal walkthrough, including problems with the roof, foundation, electrical systems, plumbing, or hidden water damage. Without an inspection contingency, if something serious turns up after you own the home, you have very limited recourse and the repair costs land entirely on you. A Middle Ground Worth Considering You do not have to choose between a full inspection contingency and no protection at all. Some buyers still get an inspection for informational purposes only, meaning they cannot negotiate based on it, but they at least know what they are walking into. Others shorten the timeline instead of waiving it entirely, or limit the negotiation to only major structural or safety issues rather than every minor item on the list. When Waiving Might Make More Sense If you are buying a newer home with a builder warranty, or a property you already know well, the risk of waiving may be lower. Buyers with a larger financial cushion who can absorb an unexpected repair are also in a different position than buyers who are stretching their budget to make the purchase work at all. When You Should Not Waive It If you are a first time buyer, working with a tight budget, or looking at an older home, keeping the inspection contingency is usually the safer choice. The goal of buying a home should not be winning the negotiation at the cost of taking on hidden problems you cannot afford to fix later. Frequently Asked Questions Q: Is waiving an inspection legal in Minnesota? A: Yes, it is legal. It is a decision made between you and your agent as part of how your offer is structured, not something prohibited by law. Q: Can I still get an inspection even if I waive the contingency? A: Yes. Many buyers get an inspection for information only, meaning they cannot use it to renegotiate or cancel, but they still learn what condition the home is in. Q: Does waiving an inspection guarantee my offer wins? A: No. It can make your offer more competitive, but sellers weigh many factors including price, financing terms, and closing timeline, not just the inspection contingency. Q: What is a shortened inspection period? A: Instead of the standard timeframe, you agree to a much shorter window, sometimes just a day or two, to complete the inspection and raise any concerns. It is a middle ground between a full contingency and waiving it entirely. Q: Can I negotiate repairs if I waived the inspection contingency? A: Generally no, since waiving the contingency removes your right to negotiate based on inspection findings. This is why the decision should not be made lightly. Q: Should my agent be involved in this decision? A: Absolutely. This is one of the most important strategy conversations to have before writing an offer, and it should be based on your specific financial situation and the specific home, not a blanket approach. Closing Call to Action Deciding whether to waive an inspection is not something to guess at. If you are preparing to make an offer and want to talk through what makes sense for your situation and the specific home you are considering, reach out to me and we will map out a strategy together.
What Is a Home Appraisal and Why Does It Matter?
You agreed on a price with the seller, your loan is moving forward, and then your lender says one more thing has to happen before closing. An appraisal. A home appraisal is an independent, professional estimate of what a home is actually worth, and your lender requires it to make sure they are not loaning you more money than the house is worth on paper. If the appraisal comes in at or above your purchase price, the process moves forward as planned. If it comes in lower, you and the seller have some decisions to make. Who Orders the Appraisal and Why Your lender orders the appraisal, not you and not the seller, even though as the buyer you typically pay for it. This is intentional. The appraiser has no relationship with either party and no stake in whether the deal closes. Their job is simply to protect the lender by confirming the home is worth roughly what you are borrowing against it. What the Appraiser Actually Looks At A licensed appraiser visits the home in person, walks through it, measures square footage, and takes note of its condition, age, layout, and any updates or deferred maintenance. They then compare it to similar homes that have recently sold nearby, often called comparable sales or comps. Location, lot size, finished basement space, garage stalls, and recent renovations all factor into the final number. What Happens When the Appraisal Matches or Exceeds the Price This is the outcome everyone hopes for. When the appraised value comes in at or above your agreed purchase price, your loan moves forward without changes needed. This confirms to your lender that the collateral behind your mortgage supports the loan amount, and it is one less thing to worry about before closing. What Happens When the Appraisal Comes in Low If the appraisal comes in below your purchase price, you have a gap to deal with. Your lender will only loan based on the appraised value, not the higher purchase price, which means you would need to cover the difference in cash, renegotiate the price with the seller, challenge the appraisal, or in some cases walk away if you have an appraisal contingency in your purchase agreement. Which option makes sense depends on how large the gap is and how much you want the home. Why the Appraisal Protects You Too It is easy to think of the appraisal as a hurdle, but it also protects you as the buyer. If a home is genuinely overpriced compared to what similar homes have sold for, the appraisal is one of the few checks in the process designed to catch that before you are locked into paying more than the home is likely worth. How to Prepare for a Smooth Appraisal There is not much you can control directly since the appraiser works for the lender, but you can help by making sure the home is accessible on the scheduled day and by working with an agent who provides the appraiser with a list of recent comparable sales and any relevant upgrades the seller has made. This kind of context can support a fair valuation. Frequently Asked Questions Q: How soon after my offer is accepted does the appraisal happen? A: It typically happens a few weeks into the process, once your loan is far enough along that your lender is ready to order it, and often after the home inspection. Q: Who pays for the appraisal? A: The buyer typically pays for the appraisal as part of closing costs or upfront fees, even though the lender is the one who orders it. Q: Can I be present during the appraisal? A: It is not required, but some buyers choose to be there. Your agent can advise on whether that makes sense for your situation. Q: What if I disagree with the appraised value? A: You can request a reconsideration of value from your lender, which involves submitting additional comparable sales data for the appraiser to review, though there is no guarantee the value will change. Q: Does a low appraisal always kill the deal? A: No. Many low appraisals get resolved through renegotiation with the seller, a buyer covering part of the gap in cash, or a combination of both. Q: Is an appraisal the same as a home inspection? A: No. An appraisal focuses on value for the lender, while an inspection focuses on the physical condition of the home for your own knowledge. They serve different purposes and are usually done separately. Closing Call to Action If you want to understand how appraisals have been playing out in the neighborhoods you are considering, or you are heading into an offer and want to think through appraisal gap strategy ahead of time, reach out to me and we can talk through it before you are in the middle of a transaction.
How Do Counteroffers Work When Buying a Home?
You submit an offer on a house you love, and instead of a yes or a no, the seller sends back a different number. Now what. That is a counteroffer, and it just means the seller wants to negotiate rather than close the door. In Minnesota, counteroffers move back and forth in writing until both sides agree on price and terms, or one side decides to walk away. What a Counteroffer Really Means When a seller receives your purchase agreement, they have three choices. They can sign it as is, reject it outright, or change something and send it back to you. That third option is the counteroffer. Legally, it cancels your original offer. The seller is not accepting your terms, they are proposing new ones, and now the decision is back in your hands. This is normal, and it does not mean your offer was bad. It usually means the seller wants to see if there is room to get a little closer to what they were hoping for before they commit. What Sellers Typically Counter On Price is the obvious one, but it is rarely the only thing on the table. Sellers might counter on the closing date if they need more time to move out, on which appliances or fixtures stay with the home, on who pays for the owner’s title insurance, or on the length of your inspection period. Sometimes a seller will accept your price but strip out a credit you asked for, or ask you to shorten a contingency deadline. Reading the counteroffer line by line matters, because the change might be more about terms than dollars. How Counteroffers Move Back and Forth Once the seller sends a counteroffer, you are not locked into it. You can accept it, which creates a binding agreement, reject it and walk away, or send your own counteroffer back. This can go a few rounds. Round one might close half the gap in price, round two might land somewhere both sides can live with, and round three might finalize small details like the closing date. Each round is its own written document, and nothing becomes binding until someone signs terms the other side has already accepted without further changes. How Long You Have to Respond Purchase agreements in Minnesota include a deadline for responding to any offer or counteroffer, often a specific date and time. If that deadline passes without a signed response, the offer expires and is no longer on the table. This is why your agent will often push for a quick turnaround, especially in a competitive market where another buyer could be negotiating on the same house at the same time. Why Sellers Negotiate Instead of Just Accepting or Declining From the seller’s side, countering keeps the deal alive while still trying to improve their position. Rejecting outright means starting over with no guarantee a better offer comes along. Accepting your first number might leave money or favorable terms on the table. A counteroffer is the middle path, and it signals that the seller is motivated to make something work with you specifically. How to Decide Whether to Counter Back or Walk Away This is where having a clear sense of your own limits helps. Before you ever submit an offer, it is worth knowing your top price and which terms actually matter to you. When a counteroffer comes in, compare it against those limits rather than reacting emotionally to the back and forth. If the gap is small and the home is right for you, another round of negotiation is usually worth it. If the seller will not move at all on something that matters to you, walking away and continuing your search is a legitimate choice, not a failure. Frequently Asked Questions Q: Can a seller send counteroffers to more than one buyer at the same time? A: In Minnesota, sellers can negotiate with multiple buyers, but each counteroffer is typically its own separate agreement. Ask your agent to confirm whether you are in a multiple offer situation so you understand the full picture before you respond. Q: Does a counteroffer cancel my original offer completely? A: Yes. Once a seller counters, your original offer is no longer available for them to simply accept later. The counteroffer becomes the active document on the table. Q: Can I counter a counteroffer? A: Yes, and it is common. You can send your own changes back, and this can continue for as many rounds as both sides are willing to negotiate. Q: Does my earnest money change during this process? A: Earnest money is not typically affected by the back and forth of counteroffers themselves. It becomes relevant once a final agreement is signed, so focus on the terms first. Q: How fast do I need to respond to a counteroffer? A: As fast as the deadline in the document requires, which can be within a day or even a few hours in a competitive market. Talk to your agent right away so you are not caught off guard. Q: Should I always try to negotiate at least once? A: Not necessarily. If the seller’s first counter is close to fair and the terms work for you, accepting can be the smarter move, especially if other interested buyers are waiting in the wings. Closing Call to Action Negotiating a counteroffer well can save you thousands of dollars or protect terms that matter to your timeline. If you are getting ready to make an offer in Minnesota, or you are already in the middle of back and forth with a seller, reach out to me and I will walk through the numbers and the strategy with you before you sign anything.
Should I Pay Off Debt or Save for a Down Payment First?
Every dollar feels like it can only do one job, so it makes sense that buyers constantly ask whether it’s smarter to pay off debt first or put that same money toward a down payment. Quick Answer: The right answer depends on the type of debt, the interest rate attached to it, and how that debt affects your debt to income ratio. In many cases, the two goals are not actually competing the way they seem to at first, and a lender can help you see the real tradeoff based on your specific numbers. Why This Isn’t Actually an Either-Or Question It is easy to frame this as a competition, debt payoff versus down payment savings, but the two goals actually serve different purposes in your mortgage approval. Your down payment affects your loan amount and, in some cases, whether you need mortgage insurance. Your debt affects your debt to income ratio, which is one of the main things a lender uses to determine how much you can borrow in the first place. Understanding what each dollar is actually doing helps you make a more informed decision than just picking one goal and ignoring the other. How Debt Affects Your Ability to Qualify Lenders calculate a debt to income ratio by comparing your monthly debt payments to your monthly income. The lower that ratio, the more room you generally have to qualify for a larger loan amount, and the more comfortable your monthly budget tends to be after you move in. Carrying high monthly debt payments, even if you have plenty of cash saved, can limit how much home you actually qualify to buy. When Paying Down Debt Should Come First If you are carrying high interest debt, like credit card balances, or if your current debt load is pushing your debt to income ratio close to a lender’s limit, focusing on debt reduction first often makes sense. Bringing that ratio down can meaningfully increase your buying power, sometimes more than adding the same amount of money to your down payment would. When Saving for a Down Payment Should Come First If your debt is limited to something like a low interest auto loan or manageable student loan payments that are not straining your ratio, and you do not yet have enough saved for a reasonable down payment and closing costs, directing extra money toward savings may get you into a home sooner. A larger down payment can also reduce or eliminate mortgage insurance depending on the loan type, which lowers your monthly payment going forward. How Debt to Income Ratio Ties It All Together Because your debt to income ratio directly affects your loan approval and the amount you qualify for, it is often the more urgent number to manage if it is close to a lender’s threshold. A lender can run your actual numbers and show you exactly how much paying off a specific debt would change your qualifying amount, which turns this from a guessing game into an actual decision based on your file. The Role of High Interest Debt Specifically Not all debt is equal here. High interest debt costs you more every month it exists and often makes the biggest difference to your debt to income ratio relative to its balance. Paying down a high interest credit card typically delivers more benefit, both to your monthly cash flow and your qualifying ratio, than putting that same money into a down payment fund. How to Build a Plan That Does Both Most buyers do not have to choose one extreme or the other. Talking with a lender early lets you build a plan that targets your highest interest or most ratio-impacting debt first, while still setting aside a portion toward your down payment on a parallel track. This kind of side by side plan is usually far more effective than picking one goal in isolation. Frequently Asked Questions Q: Does paying off all my debt guarantee me a better mortgage? A: Not automatically, but it generally improves your debt to income ratio, which can increase how much you qualify to borrow and may improve your rate depending on the overall picture. Q: Is a bigger down payment or lower debt more important? A: It depends on your numbers. A lender can show you which change, paying down a specific debt or adding to your down payment, has a bigger effect on your approval and monthly payment. Q: Does student loan debt get treated differently than credit card debt? A: Lenders look at the required monthly payment on any debt type when calculating your ratio, so the type of debt matters less than the size of the required payment relative to your income. Q: Should I drain my savings to pay off debt right before applying? A: Not usually. Lenders also want to see reserves and funds for closing costs, so it is worth talking to a lender before making a large one time payoff right before applying. Q: Can a lender actually tell me the right balance between the two for my situation? A: Yes, this is exactly the kind of question a lender can answer with your real numbers, showing you how each option changes your qualifying amount and monthly payment. Closing Call to Action If you are trying to figure out where your extra money should go right now, let’s connect you with a lender who can run your specific numbers. Having real figures in front of you makes this decision a lot easier than guessing.
What Hurts My Credit Score Most Before Applying for a Mortgage?
The months right before you apply for a mortgage are exactly when your credit score deserves the most protection, not the least. Quick Answer: A handful of common moves, opening new credit accounts, making large purchases on existing cards, missing payments, and closing old accounts, can all quietly lower your score at the worst possible time. None of these mistakes are complicated to avoid once you know to watch for them. Opening New Credit Accounts Applying for a new credit card, financing a car, or opening a store credit line all trigger a hard inquiry and add a new account to your file. Both of those can lower your score, and a new account also shortens the average age of your credit history. Even if you plan to use the new account responsibly, the timing alone can work against you if it happens close to your mortgage application. Making Large Purchases on Existing Credit Furnishing a home you have not closed on yet is one of the most common mistakes buyers make. Charging a large purchase to an existing credit card increases your credit utilization, which is a significant factor in your score. Lenders also frequently re-check credit shortly before closing, so a spike in balances between application and closing can create real problems even after you have already been approved. Missing or Making Late Payments This one seems obvious, but the stress of buying a home causes people to lose track of due dates more often than you would think. Payment history is the single largest factor in most credit scoring models, so even one missed payment in the months before applying can have an outsized effect. Set up automatic minimum payments during this period if you tend to run tight on bandwidth. Closing Older Credit Accounts It feels responsible to close a credit card you no longer use, but doing so can hurt you in two ways. It reduces your total available credit, which raises your utilization ratio even if your balances have not changed, and it can shorten your average account age over time. If you are within a few months of applying, leave old accounts open even if they are inactive. Co-Signing for Someone Else Co-signing a loan for a family member or friend adds that debt to your own credit profile and factors into your debt to income ratio, even if you are not the one making the payments. If you are planning to buy a home soon, this is not the time to take on that kind of obligation for someone else. Letting Balances Sit High Relative to Your Limits Credit utilization, meaning how much of your available credit you are actually using, matters more than most people realize. Paying down balances before you apply, rather than simply making minimum payments, can meaningfully improve your score in a fairly short window, since utilization updates as soon as your creditor reports the new balance. What to Do Instead in the Months Before Applying Keep your accounts as stable as possible. Continue paying everything on time, avoid new credit applications, keep balances low, and hold off on any major purchases until after closing. If you are unsure whether a specific financial move is safe during this window, it is worth a quick call to your lender before you act rather than after. Frequently Asked Questions Q: How far before applying should I stop opening new credit accounts? A: A good rule of thumb is to avoid new credit for at least several months before you plan to apply, and definitely once you are actively working with a lender. Q: Does getting quotes from a few different mortgage lenders count against me the same way? A: No. Mortgage-related inquiries made within a short shopping window are typically treated as a single inquiry by scoring models, which is different from opening unrelated new credit accounts. Q: Should I close a credit card I never use before applying? A: Generally no, especially close to your application. Closing an account can raise your utilization ratio and shorten your credit history, both of which can lower your score. Q: What if I already have a large purchase planned, like a car? A: Talk to your lender before making the purchase. Timing it after closing, or restructuring the plan, is often better than making a large purchase mid process. Q: Can one missed payment really affect my mortgage approval? A: Yes, particularly if it happens close to your application. Payment history carries significant weight in most scoring models, so even a single late payment can matter. Closing Call to Action If you know you’ll be applying for a mortgage in the next several months, let’s talk now rather than after something on this list has already happened. I would rather help you protect your credit ahead of time than help you recover from a surprise later.
What Credit Score Do I Need to Buy a Home in Minnesota?
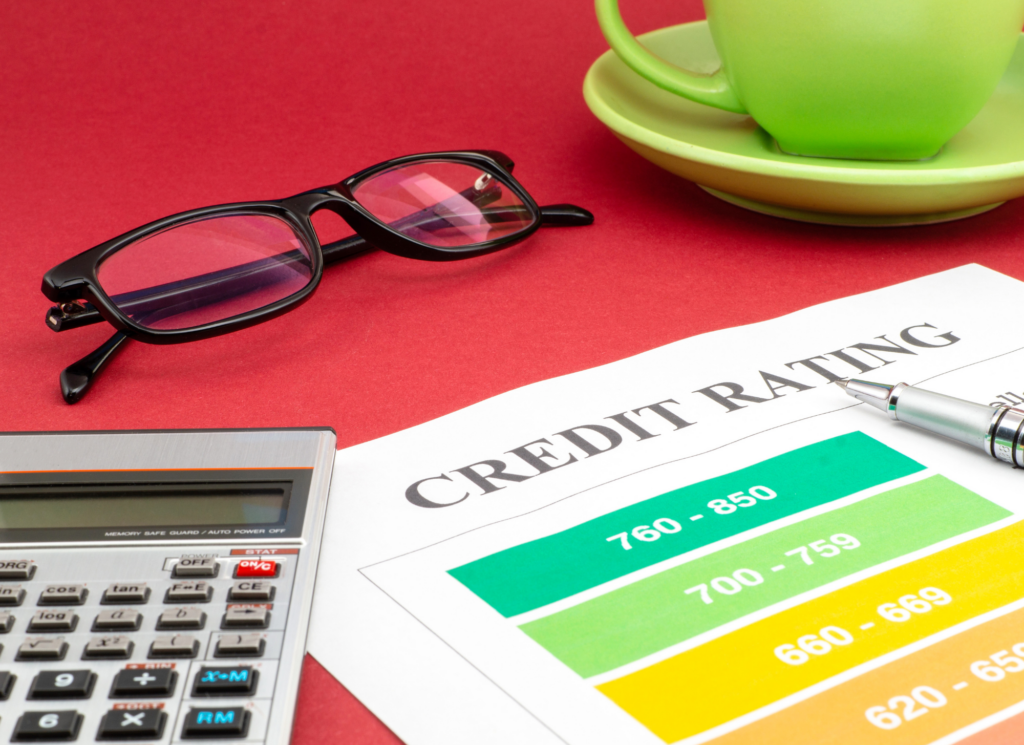
Almost every buyer I talk to asks some version of the same question early on: what credit score do I actually need to buy a house? Quick Answer: There is no single credit score requirement that applies to every buyer, because the number you need depends on the loan program you use. Different loan types set different minimum scores, and the score that gets you approved is not always the score that gets you the best rate. Understanding both matters. Why There Isn’t One Universal Number Every lender sets its own guidelines within the framework of the loan program it is offering, which means the honest answer to what score do I need always starts with it depends on the loan. A number that qualifies you for one type of financing might not qualify you for another, and two lenders offering the same loan type can still set slightly different internal minimums. How Loan Type Changes the Minimum Conventional loans, government backed loans like FHA and VA, and other programs each carry their own minimum credit score requirements set by the agencies or investors behind them. Because these requirements are updated periodically and vary by program, the most reliable way to know your exact number is to ask a lender directly which program you are being evaluated for and what that program’s current minimum is. The Difference Between Qualifying and Qualifying Well Meeting the minimum score for a loan program gets your foot in the door, but it does not necessarily get you the most competitive interest rate. Lenders typically use pricing tiers, where higher scores within the approved range unlock better rates and lower costs. This means two buyers who both qualify for the same loan can end up with meaningfully different monthly payments based purely on where their score falls. What Lenders Actually Look at Besides Your Score Your credit score is one piece of a larger picture. Lenders also look at your debt to income ratio, your employment and income history, your available cash for a down payment and reserves, and the overall pattern of how you have managed credit over time. A slightly lower score paired with strong income and low debt can sometimes still result in approval, which is why it is worth talking to a lender rather than assuming a number disqualifies you. What If Your Score Is Lower Than You Would Like If your score is below where you want it to be, that does not automatically mean buying is off the table. Some loan programs are specifically built to accommodate lower scores, often paired with other requirements like a slightly higher down payment or mortgage insurance. A conversation with a lender early, well before you plan to make an offer, gives you time to understand exactly where you stand and what your realistic options look like. How Your Score Is Actually Calculated Credit scores are built from a handful of factors: your payment history, how much of your available credit you are using, the length of your credit history, the mix of account types you have, and recent credit inquiries. Payment history and credit utilization carry the most weight, which is why consistent on time payments and keeping balances low relative to your limits tend to move the needle the most. Steps to Take Before You Apply Pull your own credit report before you talk to a lender so there are no surprises. Look for errors, outdated information, or accounts that do not belong to you, and dispute anything inaccurate. Avoid opening new credit accounts or making large purchases on existing credit in the months leading up to your application, since both can temporarily affect your score right when you need it to be stable. Frequently Asked Questions Q: Is there a specific credit score that guarantees I’ll be approved? A: No single score guarantees approval, since lenders also weigh your income, debt, and down payment together with your credit. A lender can tell you exactly where you stand for a specific loan program. Q: Does checking my own credit report hurt my score? A: No. Checking your own credit is considered a soft inquiry and does not affect your score. It is different from a lender pulling your credit for an actual application. Q: Can I buy a home in Minnesota if I have little or no credit history? A: It is more challenging but not automatically impossible. Some loan programs allow alternative ways to demonstrate creditworthiness. A lender can walk you through what that would look like for your situation. Q: How far in advance of applying should I check my credit? A: As early as possible, ideally several months before you plan to apply, so you have time to correct errors or make improvements if needed. Q: If I pay off a credit card balance, will my score go up right away? A: Often yes, since credit utilization is a significant factor, but the exact timing depends on when your creditor reports the updated balance, which is not always instant. Closing Call to Action If you are wondering where your credit actually stands and what that means for the loan programs available to you, let’s talk before you start house hunting. I can point you toward a trusted lender who will give you real numbers instead of guesswork.
What Is a Mortgage Rate Lock and When Should I Use One?
You found a rate you like, your lender mentions locking it in, and suddenly you’re being asked to make a decision you didn’t know you’d have to make yet. Quick Answer: A mortgage rate lock is an agreement with your lender that guarantees a specific interest rate for a set period of time while your loan moves through processing and underwriting, protecting you from rate increases during that window. You generally want to lock once you are under contract on a home and have a realistic closing date in view, not before. What a Rate Lock Actually Does Mortgage rates move throughout the day based on the bond market, and they can shift meaningfully over the weeks it takes to close on a home. A rate lock is your lender’s written commitment that the rate you agreed to will not change during a set window, regardless of what happens in the broader market between now and closing. Without a lock, the rate you were quoted is not guaranteed until you actually secure one. How Long a Typical Lock Period Lasts Lock periods are usually offered in set increments, commonly somewhere in the range of thirty to sixty days, though longer options exist for certain situations like new construction. Your lender will recommend a lock period based on your expected closing date, and it is worth padding that estimate slightly rather than cutting it close, since delays in underwriting, appraisal, or title work are common and not always within your control. What Happens If Rates Drop After You Lock This is the part that catches buyers off guard. Once you lock, you are generally committed to that rate even if the market improves before closing. Some lenders offer a float-down option that lets you capture a lower rate if one becomes available, but that is not automatic and often comes with its own fee or conditions. Ask specifically whether your lock includes this option before you sign anything. What Happens If Your Closing Gets Delayed If your closing pushes past the end of your lock period, you may need to extend it, and extensions can come with a fee depending on the lender and how long the extension needs to be. This is one more reason to build a little breathing room into your original lock period, especially if you are buying new construction or your closing depends on a chain of other transactions. Is There a Cost to Locking Your Rate Some lenders build the cost of a rate lock into the rate itself with no separate fee, while others charge a small fee for longer lock periods or for float-down protection. This varies by lender, so ask directly what your specific lock includes and what it would cost to extend it if needed. When Is the Right Time to Lock in Minnesota In most cases, the right time to lock is after you are under contract on a specific home and have a target closing date from your purchase agreement. Locking too early, before you have an accepted offer, means you could be tying yourself to a rate for a home you never end up buying. Locking too late leaves you exposed to rate movement right when you can least afford surprises. What to Ask Your Lender Before You Lock Ask how long the lock lasts, what it costs to extend if needed, whether a float-down option is available, and what happens if your closing date changes. Getting clear answers to these questions before you lock means fewer surprises later in the process. Frequently Asked Questions Q: Can I lock in a rate before I’ve found a home? A: Most lenders require you to be under contract on a specific property before locking, since the lock is tied to the loan for that transaction. Q: What happens if my closing date gets pushed back? A: You may need to extend your lock, which can come with a fee depending on your lender and how long the delay is. Ask about extension costs before you lock. Q: Do all lenders charge a fee to lock a rate? A: It varies. Some build the lock into the rate with no separate charge, while others charge for longer terms or added features like a float-down. Ask your specific lender. Q: If I switch lenders after locking, do I keep my locked rate? A: No, a rate lock is tied to the lender you locked with. Switching lenders means starting the lock process over with the new one. Q: What is a float-down option? A: A float-down lets you take advantage of a lower rate if the market improves after you lock, usually for an added fee or under specific conditions. Not every lender offers it, so ask directly. Closing Call to Action If you are getting close to making an offer and want to understand how rate locks fit into your specific timeline, reach out to me. I can help you think through the timing so you are not caught off guard during underwriting.
Should I Use My Bank or a Mortgage Broker in Minnesota?
Somewhere between deciding you want to buy a home and actually filling out a loan application, almost every Minnesota buyer hits the same question: do I call the bank I already have, or do I find a mortgage broker instead? Quick Answer: There is no universal right answer here. A bank lends you its own money using its own set of loan products, while a mortgage broker works with several different lenders and shops your application around to find a fit. Both can get you to closing with a good rate. The better choice usually comes down to your credit profile, how complicated your income is, and whether you want to do the comparison shopping yourself or have someone else do it for you. What You’re Actually Getting From a Bank When you go through your bank or another direct lender, you are working with one institution from start to finish. They underwrite the loan in house, they hold the relationship, and in many cases they service the loan after closing too. If you already have a strong relationship with a local bank or credit union, that can mean faster communication and someone who already knows your financial history. The tradeoff is that you are only seeing one set of rates, one set of guidelines, and one appetite for risk. If your file does not fit neatly into what that bank prefers to lend on, you may hear no even though another lender would have said yes. What a Mortgage Broker Actually Does A broker is not a lender. They are a licensed professional who takes your financial information once and shops it to a network of wholesale lenders on your behalf. Instead of you calling five different banks and filling out five applications, the broker does that comparison for you and brings back the offers that make sense. Brokers are paid either by the lender or by you as the borrower, and Minnesota law requires that fee to be disclosed up front. Because they work with multiple lenders, brokers often have more flexibility for buyers with less common income, lower credit scores, or unusual property types. Where a Bank Tends to Make Sense If your income is straightforward, your credit is solid, and you already bank somewhere you trust, going direct can be simple and efficient. You skip an extra layer of communication, and if you have other accounts or a mortgage history with that institution, they may already have some of your documentation on file. Buyers who value one point of contact from application through closing often prefer this route. Where a Broker Tends to Make Sense If you are self-employed, have irregular income, are working with a lower credit score, or simply want to see rates from more than one source before committing, a broker can save you real time and legwork. Because they are not tied to one lender’s guidelines, they are often better positioned to find a loan program that fits a more complicated financial picture. If your last experience with a single bank ended in a denial, a broker is usually the next call worth making. Comparing Rates and Fees the Right Way Whichever route you choose, do not compare offers by interest rate alone. Ask for a full loan estimate that shows the rate, the fees, and the closing costs together, and compare those documents side by side. A slightly lower rate paired with higher fees is not automatically the better deal. Getting quotes within the same short window also matters, since it limits how many separate credit inquiries show up and keeps the comparison fair. Questions Worth Asking Before You Commit Ask any lender or broker how they are compensated, what loan programs they have access to, and how quickly they can close. Ask for references from recent Minnesota closings if you can. And ask what happens if your file runs into an issue mid process. How that question gets answered often tells you more about who you are working with than the initial rate quote does. Frequently Asked Questions Q: Does going through a broker cost me more than going straight to a bank? A: Not necessarily. Broker compensation is built into the loan structure and disclosed on your loan estimate, so you can compare the full cost side by side with a bank’s offer rather than assuming one is automatically more expensive. Q: Can I talk to a bank and a broker at the same time? A: Yes, and many buyers do exactly that. Getting quotes from both within the same short window lets you compare real numbers instead of guessing which path is better. Q: Will getting quotes from multiple lenders hurt my credit score? A: Mortgage-related credit inquiries made within a short window are generally grouped together by scoring models as a single inquiry, so shopping around within that window has a much smaller impact than people expect. Q: Does my own bank automatically give me the best rate since I’m already a customer? A: Not automatically. Loyalty can help with service and communication, but it does not guarantee the most competitive rate. It is still worth comparing. Q: I’m self-employed. Does that change which option makes more sense? A: It can. Self-employed and commission-based buyers often have more paths available through a broker, since brokers can shop your file to lenders whose guidelines are built around non-traditional income. Closing Call to Action Whether you are leaning toward your bank, a broker, or you genuinely are not sure yet, I would rather you ask the question before you apply than after you get a surprise denial. Reach out to me and I will walk you through what makes sense for your specific situation as you start the Minnesota homebuying process.