
Can I Use Multiple Co-Borrowers to Qualify for a Mortgage?
Your income alone might not stretch as far as you want it to, and you are wondering if bringing family or a partner onto the loan could change what you actually qualify for. Quick answer: Yes, many loan programs allow more than one co-borrower on a mortgage. Adding additional qualified borrowers can increase your combined income and improve what you qualify for, but every person on the loan also needs to meet the lender’s credit and documentation requirements. What a Co-Borrower Actually Is A co-borrower is someone who joins you on the mortgage application and shares full responsibility for repaying the loan. Their income, debts, and credit history are all factored into the lender’s decision, and their name will appear on the loan alongside yours. This is different from a co-signer, who typically supports the loan without necessarily being on the property title, so it is worth understanding which role each person is actually stepping into. How Multiple Co-Borrowers Can Strengthen Your Application Combining incomes can help you qualify for a larger loan amount, and if one borrower has a stronger credit history, it can sometimes help the overall file, depending on how the lender evaluates the group. This is one of the more common strategies used by families buying together, whether that means a spouse, a sibling, a parent, or another close family member joining the application. Every Co-Borrower Needs to Meet Documentation Requirements Adding a co-borrower does not simplify your paperwork, it usually doubles it. Each person on the loan needs to provide their own income documentation, credit history, and proof of funds if they are contributing financially. Before you assume a second or third borrower will make qualifying easier, make sure that person is prepared to go through the same documentation process you are. How Lenders Evaluate Combined Credit Histories Different loan programs handle multiple borrowers’ credit differently. Some use the lowest qualifying credit score among the group, while others may look at each borrower’s file individually for certain purposes. This is an important detail to ask your lender about directly, since it can significantly affect your interest rate and the loan programs you are eligible for. What Happens if One Co-Borrower Has Weaker Credit or Income Adding a co-borrower is not always a guaranteed improvement. If one person’s credit history or debt load is significantly weaker than the primary borrower’s, it can sometimes work against the file rather than strengthening it. This is why it helps to review each potential co-borrower’s financial picture honestly before deciding who should be included on the application. Non-Occupant Co-Borrowers and How They Differ Some loan programs allow a non-occupant co-borrower, meaning someone who helps you qualify financially but does not plan to live in the home. This is common when a parent or family member wants to help an adult child qualify for their first home. The requirements and limits on this arrangement vary by loan program, so it is worth discussing early with your lender if this is the direction you are considering. Working With a Lender to Structure the Right Application Because adding co-borrowers changes both the math and the paperwork of your application, it helps to talk with a lender before you decide who will be included. They can run different scenarios and show you how your qualifying amount changes depending on who joins the loan, which gives you a clearer picture before you start touring homes with a specific number in mind. Frequently Asked Questions Q: Is there a limit to how many co-borrowers I can add? A: Most loan programs allow multiple co-borrowers, though there can be practical and program specific limits. Your lender can confirm what applies to your situation. Q: Do all co-borrowers need to live in the home? A: Not necessarily. Some loan programs allow a non-occupant co-borrower who helps you qualify financially without living in the property. Q: What happens if a co-borrower has poor credit? A: Depending on the loan program, this can lower the qualifying credit score used for the application, which may affect your interest rate or eligibility. Q: Can co-borrowers be removed from the loan later? A: In most cases, removing someone from a mortgage requires refinancing the loan entirely, since the original agreement includes all borrowers. Q: Does everyone on the loan need to be on the title? A: Typically yes, though the specifics can vary. This is an important detail to clarify with both your lender and a real estate attorney before closing. If you are working through this exact question, reach out to me and let’s go over your specific situation together. I will help you understand what your file needs and guide you through it step by step.
What If My Income Is Paid in Cash? Can I Still Buy a Home?
You work hard, you get paid, and the money happens to come to you in cash. That does not shut the door on homeownership, but it does mean you need to handle your finances a little differently starting now. Quick answer: Yes, you can still buy a home if you are paid in cash, but you will need to document that income properly. That usually means depositing your earnings consistently into a bank account and, when possible, reporting that income on your taxes so there is an official record a lender can rely on. Why Cash Income Creates Extra Steps Lenders cannot verify income they cannot see. A pay stub or a direct deposit creates an automatic record, but cash in hand does not, unless you take the extra step of depositing it and reporting it. This does not mean cash income disqualifies you. It means you need to build the paper trail yourself instead of relying on an employer to generate one for you. The Importance of Depositing Your Income Regularly The single most useful habit you can build is depositing your cash income into the same bank account on a consistent schedule. A pattern of regular deposits, ideally matching how often you are paid, gives a lender something concrete to look at. Irregular or inconsistent deposits are much harder to document convincingly, even if the income itself is completely legitimate. Why Reporting This Income on Your Taxes Matters Lenders lean heavily on tax returns to verify income, particularly for anyone whose pay is not automatically reported through a W-2. If your cash income is reported on your tax return, it becomes part of your official income history and is far easier for an underwriter to count toward your qualifying income. Unreported income, even if real, is very difficult for a lender to use, since they have no official record to point to. Working With Your Tax Preparer Before You Apply If you know you want to buy a home in the near future, it is worth having a conversation with whoever prepares your taxes about how your income is being reported. Getting ahead of this by a year or two, rather than trying to fix it right before applying, gives you a documented history that a lender can actually use. What Additional Documentation Can Help Your File Beyond tax returns and deposit history, additional support can include a letter from your employer confirming your role and typical pay, invoices if you do contract style work, or a written log of hours and payments if your work does not generate formal paperwork on its own. The more consistent documentation you can provide, the stronger your file becomes. How Lenders Calculate Income From Cash Pay Lenders will generally look at your reported and documented income over a period of time, similar to how they evaluate self-employed or gig income, and use an average rather than your best month. If your documented income has been thin in the past, it may take a little more time to build up a strong enough history to qualify for the loan amount you want. Working With a Lender Who Understands This Situation Being paid in cash is common in many industries, and an experienced lender has seen it before. They can tell you early on exactly what your file is missing and give you a realistic timeline for building the documentation you need, rather than leaving you guessing about whether you are even eligible to apply. Frequently Asked Questions Q: Can I use cash income if I have never reported it on my taxes? A: It becomes much harder to document. Talk to a tax professional about getting current on reporting before you apply for a mortgage. Q: How long should I be depositing my income before I apply? A: Many lenders want to see a consistent pattern over roughly two years, though some flexibility exists depending on the loan program. Q: Does it matter which bank account I deposit into? A: It should be an account in your name that you can provide statements for. Using the same account consistently makes your pattern easier to verify. Q: Can I combine cash income with a regular W-2 job? A: Yes, and doing so often strengthens your file, since it adds a documented, verifiable income source alongside your cash earnings. Q: Will a lender ask why I was paid in cash? A: They may ask general questions about your work, but the bigger focus is on whether your income is documented and consistent, not on judging how you were paid. If you are working through this exact question, reach out to me and let’s go over your specific situation together. I will help you understand what your file needs and guide you through it step by step.
How Do Lenders Verify Overseas Employment History?
You built a solid career before you ever set foot in Minnesota, and now you are wondering if any of that work history actually counts toward getting approved for a mortgage. Quick answer: Yes, overseas employment history can often count, especially if you are newly established in the U.S. Lenders typically ask for a written reference or verification letter from your former employer, along with any pay documentation you can provide, to help fill in the gap before your U.S. work history begins. Why Overseas Employment Matters to a Lender Lenders want to see continuity. A gap in your work history can raise questions, even if the truth is simply that you were building a career in another country before relocating. Providing documentation of your overseas employment helps a lender see a continuous, believable story about your income and your ability to hold steady work, rather than a resume that appears to start the day you arrived. What a Verification Letter Should Include A strong verification letter from a former employer typically includes your job title, your dates of employment, a general description of your responsibilities, and, if possible, your compensation. It helps if the letter is on official letterhead and signed by someone in a position to confirm this information, such as a manager or someone in human resources. The more specific and official it looks, the easier it is for an underwriter to accept at face value. Translating and Certifying Foreign Documents If your employment documentation is in another language, it will generally need to be translated, and in many cases certified as an accurate translation. This is a standard requirement, not a red flag specific to your situation. Ask your lender early which translation standard they require so you are not stuck redoing paperwork close to a deadline. When You Do Not Have a Formal Letter Available Sometimes a former employer is difficult to reach, especially if time has passed or the company has changed significantly. In these cases, alternative documentation such as old pay records, tax documents from that country, or even a personal letter explaining your role alongside any other proof you have can sometimes be used. This is exactly the kind of situation where a letter of explanation, paired with whatever supporting paperwork exists, can help move your file forward. How This Fits Into Your Overall Income Picture Overseas employment history is rarely used on its own. It is typically combined with your current U.S. income and employment to build a complete picture for the underwriter. If you started a new job in Minnesota recently, your prior overseas work can help explain your career trajectory and support the idea that your current position is a natural continuation of your professional background rather than a sudden change. Common Reasons This Process Slows Down The most common delay happens when documentation is incomplete or when a former employer takes a long time to respond to a verification request. Starting this process early, ideally before you are deep into house hunting, gives you time to track down documents or find alternative ways to verify your history if the first attempt does not go smoothly. Working With a Lender Who Has Seen This Before A lender who regularly works with newly arrived buyers will usually know exactly what format of verification letter satisfies their underwriting guidelines, and can tell you early whether your documentation is likely to be sufficient. That kind of guidance early in the process can save you weeks of uncertainty later. Frequently Asked Questions Q: Do I need a letter from every employer I have ever had overseas? A: Usually just your most recent employer or employers covering the period a lender needs to verify, which is often the past couple of years. Q: What if my former employer will not provide a letter? A: Talk to your lender about alternative documentation, such as old pay records or tax paperwork from that country, combined with a written explanation. Q: Does my overseas job need to be in the same field as my current job? A: It helps if there is a clear connection, but it is not always required. A lender is mainly trying to confirm that you have a consistent history of steady employment. Q: Do foreign documents need to be certified, or just translated? A: Requirements vary by lender. Some require certified translations, while others accept a standard translation with a signed statement of accuracy. Ask early. Q: Will this process delay my closing timeline? A: It can, if you wait until the last minute to gather documentation. Starting early is the best way to avoid unnecessary delays. If you are working through this exact question, reach out to me and let’s go over your specific situation together. I will help you understand what your file needs and guide you through it step by step.
Can I Qualify for a Mortgage With Contract or Gig Income?
You are working hard, the money is coming in every week, and yet the idea of qualifying for a mortgage with gig or contract income feels like a question mark nobody has answered clearly for you. Quick answer: Yes, contract and gig income can qualify you for a mortgage. Lenders just look at it differently than a traditional paycheck. Instead of a single pay stub, they want to see a consistent pattern of income over time, usually documented through tax returns, 1099 forms, or bank deposits that tell a steady story. Why Lenders Treat Contract Income Differently A traditional employee has an offer letter, a set salary, and pay stubs that show the exact same amount every pay period. Contract and gig income does not work that way, so lenders rely on a different set of documents to reach the same conclusion, that your income is real and likely to continue. This usually means looking at a longer history, since a single strong month does not tell them much on its own. What Documentation Actually Helps Your File The strongest files include recent tax returns, 1099 forms from the platforms or clients you work with, and bank statements showing deposits that match those documents. If you invoice clients directly, keep copies of those invoices alongside proof of payment. The goal is to build a picture where your tax paperwork, your invoices, and your bank deposits all tell the same consistent story without contradicting each other. How Long of an Income History Do You Need Most lenders want to see a income history of around two years in the same line of work, though there is some flexibility if you can show a clear transition from a related field or if your income has been consistent even over a shorter stretch. If you are newer to contract or gig work, talk to your lender early so you understand exactly what they need to see before you assume you are not ready to apply. How Lenders Calculate Your Qualifying Income Lenders typically average your income over the documented period rather than using your best month or your most recent month alone. If your income has grown steadily, that trend can work in your favor. If it has been inconsistent, expect the lender to use a more conservative average. Understanding this ahead of time helps you set realistic expectations for how much home you can qualify for. Deductions on Your Tax Return Can Work Against You This is one of the most common surprises for self-employed and gig workers. Lenders generally look at your net income after business deductions, not your gross earnings before expenses. If you have taken aggressive deductions to lower your tax bill, that same strategy can lower the income a lender is willing to count. It is worth having a conversation with your tax preparer and your lender together before you file, if you know a home purchase is coming up. Combining Gig Income With Other Income Sources Many buyers do not rely on gig or contract income alone. If you also have a part-time W-2 job, rental income, or another documented source, all of it can typically be combined to strengthen your file. The key is making sure every source is properly documented rather than assuming a lender will simply take your word for an income stream that is not backed by paperwork. Working With a Lender Who Understands Nontraditional Income Not every lender is comfortable underwriting contract or gig income, and some will ask for far more back and forth than necessary simply because they do not see it often. A lender who regularly works with self-employed and gig workers usually knows exactly which documents will move your file forward quickly, which saves you time and frustration during a process that already has enough moving parts. Frequently Asked Questions Q: Can I qualify with only one year of gig income history? A: It depends on the lender and your specific situation. Some programs allow it if you can show a clear pattern or a related work history, but two years is the more common standard. Q: Will my lender use my gross income or my net income? A: Most lenders use your net income after business expenses and deductions, which is why aggressive tax deductions can sometimes lower your qualifying income. Q: Can I combine income from multiple gig platforms? A: Yes, as long as each source is documented with tax forms or statements that show a consistent pattern over time. Q: Do I need an accountant to help with this process? A: It is not required, but having organized, professionally prepared tax returns often makes your file move more smoothly through underwriting. Q: What if my gig income has grown a lot in the last year? A: Growth can work in your favor, but be prepared to explain it. A lender may still average your income across the documented period rather than relying only on your most recent numbers. If you are working through this exact question, reach out to me and let’s go over your specific situation together. I will help you understand what your file needs and guide you through it step by step.
What Is Proof of Funds and How Do I Show It to a Lender?

Every lender asks for it sooner or later, and almost every buyer gets a little nervous the first time they hear the phrase: proof of funds. Quick answer: Proof of funds is simply documentation showing you actually have the money you say you have for your down payment and closing costs, usually recent bank statements or account statements that a lender can trace back to a legitimate source. It is not complicated, but lenders are strict about how it is presented. What Proof of Funds Actually Means Proof of funds is exactly what it sounds like. It is documentation that confirms the money sitting in your account is real, available, and yours. Lenders are not trying to make your life difficult. They are required to verify that the down payment and closing funds you plan to use actually exist and are not borrowed from an undisclosed source right before closing. For most buyers, this means recent statements from checking, savings, or investment accounts that clearly show your name, the account number, and a running balance over the past couple of months. Which Accounts and Documents Count Checking and savings accounts are the most common source, but retirement accounts, brokerage accounts, and certificates of deposit can often count too, depending on the loan program and how liquid the funds are. What matters most is that the statement is complete. Lenders want every page of a statement cycle, not just a screenshot of a balance. A balance alone tells them nothing about where the money came from or how long it has been sitting there, and both of those details matter just as much as the number itself. How Lenders Verify What You Send Them Once you submit your statements, an underwriter will look at the transaction history, not just the ending balance. They are checking for consistency between your income and your deposits, and they are looking for anything that seems out of place. If your paycheck deposits look normal and your balance grows steadily over time, that is an easy file to approve. If there is a sudden jump that does not match your regular income pattern, expect a follow up question asking you to explain and document where that specific deposit came from. Large or Unusual Deposits and Why They Get a Second Look A large deposit is not automatically a problem, but it is automatically going to get noticed. Underwriters are trained to flag deposits that do not match your typical income, and they will ask for a paper trail. This might be a bill of sale if you sold a vehicle, a letter and documentation if it was a gift, or a statement from another account showing the transfer if you moved money between your own accounts. The fastest way to slow down your file is to leave a deposit unexplained and hope nobody asks about it. Someone always asks. What Happens When Some of Your Funds Come From Overseas If part of your down payment is coming from an account outside the United States, you will likely need additional documentation showing the funds left that account and landed in a U.S. bank in a traceable way. This can include the foreign statement showing the withdrawal, wire transfer confirmation, and a U.S. statement showing the deposit arriving. Currency conversion does not create a problem on its own. What lenders want is a clear line from point A to point B with no unexplained gaps in between. Timing Your Documentation Before You Apply The earlier you start gathering these documents, the smoother your file will move. Some lenders want to see that funds have been sitting in your account for a set period before you apply, which is often called seasoning. If you know you are planning to buy in the coming months, it helps to consolidate your funds into the accounts you plan to use for the purchase and let them sit undisturbed rather than moving money around right before you submit your application. Working With a Lender Who Reviews Files Like Yours Regularly Not every loan officer sees international deposits or nontraditional income on a weekly basis, and that experience gap shows up in how smoothly your file moves through underwriting. A lender who regularly works with buyers in situations similar to yours will usually tell you exactly what to gather before you even submit your application, which saves you from a back and forth that can add real delay to your closing timeline. Frequently Asked Questions Q: How many months of bank statements do I need to provide? A: Most lenders ask for the two most recent months, though some may request more depending on your loan program. Always send full statements, including every page, rather than a partial screenshot. Q: Does a large deposit automatically get flagged? A: Any deposit that does not clearly match your regular income pattern usually draws a follow up question. It does not disqualify you, it just means you will need to document where the money came from. Q: Can I use money from a retirement account as proof of funds? A: In many cases yes, though the rules vary by loan program and by how accessible those funds actually are. Your lender can tell you exactly how that account will be treated. Q: Do gift funds count as proof of funds? A: Yes, but they usually require a signed gift letter along with documentation showing the money moving from the giver’s account to yours. Q: What if my proof of funds includes money from more than one account? A: That is common and generally fine. You will just need statements for each account and, if funds were consolidated recently, documentation showing that transfer as well. If you are working through this exact question, reach out to me and let’s go over your specific situation together. I will help you understand what your file needs and guide you through it step by step.
What Is It Like Living in the Outer Twin Cities Suburbs?
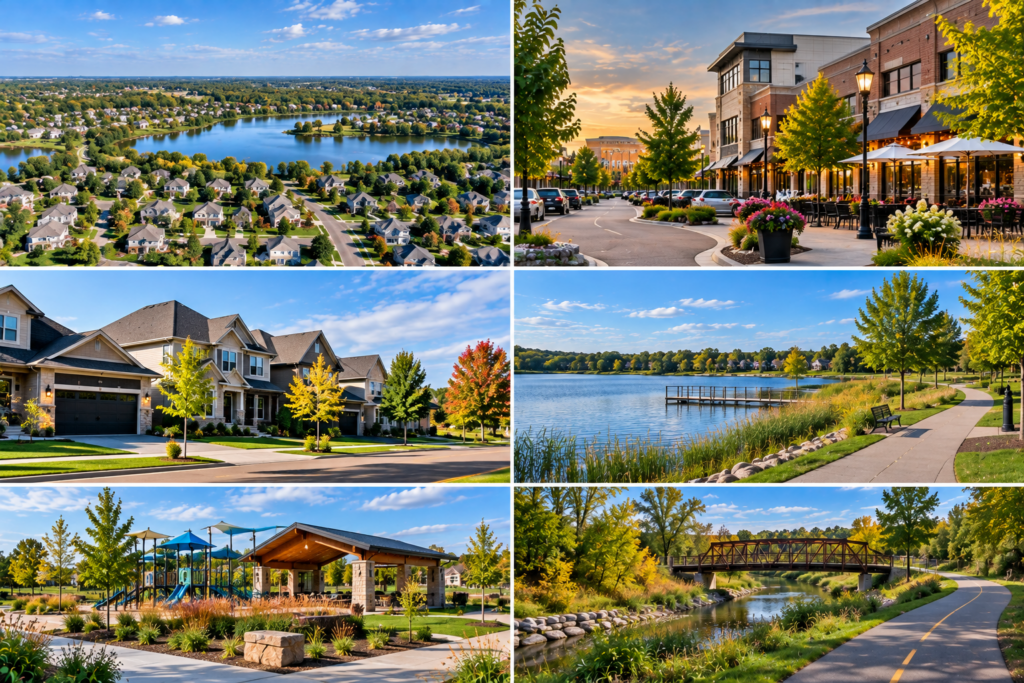
A growing number of my clients start their search close to the core cities and end up widening their radius once they see what their budget actually buys once you cross into the outer ring suburbs, and that shift in expectations is usually the moment the search actually starts moving forward. The quick answer: the outer Twin Cities suburbs generally trade a longer commute for more space, newer construction, and a lower price per square foot compared to the inner ring, and that tradeoff works well for buyers who value room to grow over a short drive downtown. It is a tradeoff, not a downgrade, and plenty of buyers end up happier out here than they expected. What Counts as the Outer Ring The outer Twin Cities suburbs generally sit a ring beyond the more established, closer in suburbs, in cities like Rogers, Otsego, Elk River, Hugo, Forest Lake, Farmington, Lakeville, and similar communities spread around the edges of the metro. These cities are not rural in the traditional sense, they still have schools, retail, and organized neighborhoods, they just sit farther from the urban core and often still have room to grow. Commute Reality The tradeoff that comes with the outer ring is almost always commute time. A drive into downtown Minneapolis or St. Paul from these cities typically takes longer than from an inner ring suburb, and traffic patterns can make that drive considerably longer during peak hours. Buyers who work from home, work locally, or only commute a few days a week tend to feel this tradeoff far less than someone driving downtown five days a week, so it is worth mapping your actual work schedule against the commute before assuming it will or will not be a dealbreaker. Housing Stock and New Construction One of the biggest draws of the outer ring is new construction. These cities generally have more available land, which means more new subdivisions, more modern floor plans, and often more house for the same budget compared to a similarly priced home closer to the core. Buyers who want a newly built home with current finishes and an efficient layout often find the outer ring gives them more options than the inner suburbs, where available land for new development is much more limited. Cost and Value Generally speaking, the outer ring suburbs offer a lower price per square foot than the inner ring and core cities, which is the main reason so many buyers end up widening their search in this direction. That said, pricing still varies significantly by city and neighborhood, and the gap has narrowed in some of the more popular outer suburbs as demand has increased, so it is worth comparing actual listings rather than assuming every outer suburb is dramatically cheaper. It is also worth factoring in the cost of a longer commute, since extra fuel and drive time are real costs even if they do not show up on a closing statement. Schools Outer ring suburbs are typically served by their own local school districts, which vary in size and reputation just as much as districts closer to the core. Because many of these communities have grown quickly, some districts have had to expand facilities to keep up with enrollment, so it is worth asking about current capacity and any planned changes when touring a specific area. Community Feel and Growth A lot of outer ring suburbs still have a visible growth phase happening, with new developments, expanding retail, and infrastructure still catching up to residential growth in some cases. That gives these communities a different feel than a fully built out inner suburb, more in progress, with new amenities arriving steadily rather than everything already established. Some buyers love watching a community grow around them, while others prefer the more finished feel of an established suburb. Amenities and Daily Life Retail and dining have expanded significantly in a lot of outer ring communities over the past decade, though residents may still occasionally drive into a neighboring city or closer to the core for certain specialty stores or entertainment options that have not yet arrived locally. Parks and trail systems are often a strong point in these newer developments, since many were planned with green space built in from the start rather than added later, which gives a lot of outer ring neighborhoods a genuinely open, green feel that some older, more built out suburbs cannot match. Who Tends to Thrive Out Here In my experience, buyers who do best in the outer ring are the ones prioritizing space, new construction, and value per square foot over a short commute, along with people who work from home or have flexible schedules that make an occasional longer drive less of a daily burden. Buyers who want a bigger yard and a newer home, and who are comfortable planning ahead for errands that might require a slightly longer drive, tend to be very happy out here. Questions Worth Asking Before You Commit Before writing an offer in an outer ring community, I encourage buyers to ask about planned road and infrastructure improvements, since some of these cities are still catching up to their own residential growth. It is also worth asking how the local school district is handling enrollment growth, and whether any new schools or expansions are planned. Finally, actually drive the commute you would be making regularly, at the time of day you would be making it, rather than relying on a map estimate that does not account for real traffic patterns. Frequently Asked Questions What cities count as outer ring Twin Cities suburbs? Cities like Rogers, Otsego, Elk River, Hugo, Forest Lake, Farmington, and Lakeville are commonly considered part of the outer ring, though the exact boundary is more of a general concept than an official line. Is it cheaper to buy in the outer ring suburbs? Generally yes, on a price per square foot basis, though the gap varies by city and has narrowed in
What Is It Like Living in Suburban Minnesota vs Rural Minnesota?
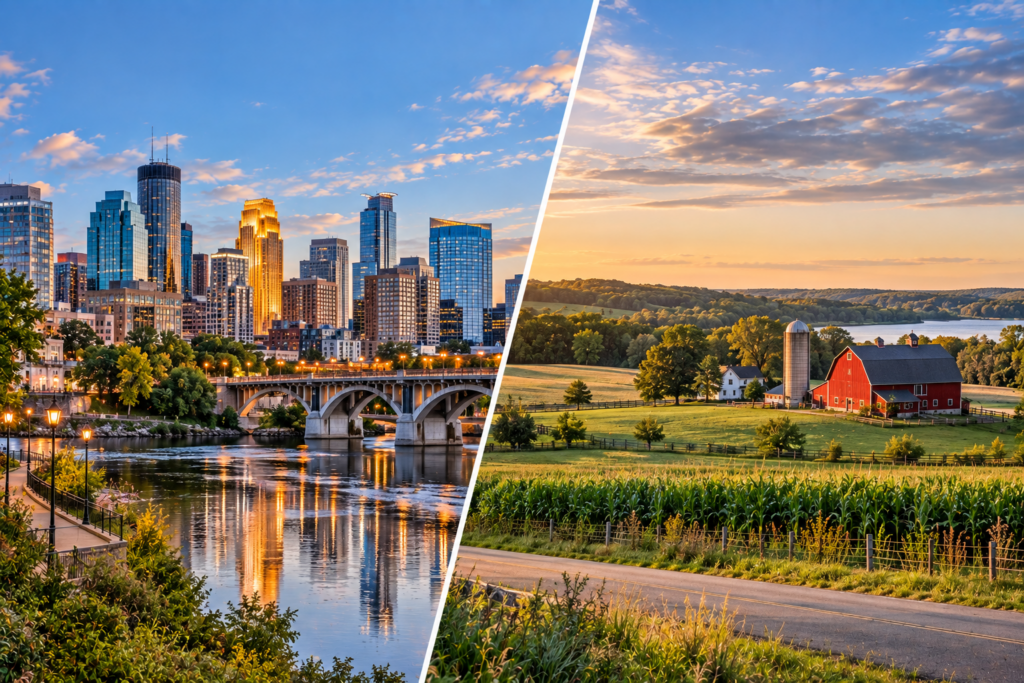
Every year I work with a handful of buyers torn between staying in the suburbs and moving farther out to something more rural, and it usually comes down to picturing two very different versions of daily life without ever having lived either one, which makes this one of the harder decisions to talk through honestly. The quick answer: suburban Minnesota offers convenience, shorter commutes, and easy access to shopping, schools, and services, while rural Minnesota trades some of that convenience for space, quiet, and a slower pace of life that suits a different kind of buyer entirely. Neither one is objectively better, it comes down to what your everyday life actually needs. What Suburban Life Actually Looks Like Suburban living in Minnesota generally means a home on a standard sized lot, sidewalks or nearby trails, and a short drive to grocery stores, schools, and most everyday errands. Neighborhoods tend to be organized around school districts and commercial corridors, so daily life has a predictable rhythm built around commuting, errands, and nearby amenities. For a lot of buyers, especially those with kids or a regular office commute, that predictability is exactly the point. What Rural Life Actually Looks Like Rural Minnesota living usually means more acreage, more distance between neighbors, and a longer drive for groceries, school, or a night out. Buyers who choose this route are often looking for space for animals, gardening, hobbies, or simply the quiet that comes with fewer neighbors and less traffic. It also means taking on more responsibility for things a suburban homeowner might not think about, like well water, septic systems, or long driveways that need to be maintained through a Minnesota winter. Some buyers find this tradeoff freeing, while others do not fully appreciate what it involves until they have already lived with it for a season or two. Commute and Access to Amenities This is usually the biggest practical difference between the two. Suburban residents can typically reach a grocery store, urgent care, or a school within a matter of minutes, and commuting into the core cities, while not always short, is at least a known and manageable quantity. Rural residents often accept a longer drive for basic errands as part of the deal, and healthcare, shopping, and entertainment options may require planning ahead rather than a quick trip whenever something comes up. Housing and Land Suburban homes typically sit on lots measured in fractions of an acre, with land use governed by fairly standard city zoning and homeowners association rules in some developments. Rural properties can range from a few acres to much larger parcels, and buyers moving from a suburban environment are often surprised by how differently rural land is priced, taxed, and maintained compared to a typical suburban lot. Schools and Community Services Suburban school districts tend to be larger, with more programming options and often newer facilities funded by a bigger tax base. Rural school districts are frequently smaller, which some families see as a benefit because of smaller class sizes and a closer knit community, while others worry about fewer program offerings. Emergency services, similarly, tend to have faster response times in suburban areas simply due to proximity, which is worth factoring in for buyers considering a more remote property. Cost Considerations Land itself is often more affordable per acre in rural areas compared to suburban lots, but that does not always translate into a lower overall cost of living once you account for longer commutes, higher fuel costs, and the expense of maintaining wells, septic systems, and larger properties. Suburban living often comes with a higher price per square foot but lower ongoing maintenance responsibility, since city services handle things like water, sewer, and road maintenance that rural homeowners typically manage themselves. Pace of Life and Community Feel Suburban Minnesota tends to move at a busier, more scheduled pace, with more organized activities, more traffic, and more going on within a short drive at any given time. Rural Minnesota moves more slowly by comparison, with community built more around smaller local events, neighbors who genuinely know each other, and a level of quiet that some buyers find restorative and others find isolating. Neither pace is right or wrong, it really depends on what kind of daily rhythm actually suits you. Winter Considerations for Each Setting Minnesota winters affect both settings, but not in exactly the same way. Suburban residents typically benefit from city snow removal on main roads and shorter drives if conditions get rough, which keeps daily life more predictable even during a heavy storm. Rural residents are often responsible for clearing their own driveway, sometimes a long one, and may need to plan around slower plowing on township or county roads compared to a city street. Anyone considering a rural property should ask directly about winter maintenance responsibilities before making an offer, since it affects both cost and daily convenience. Which One Should You Actually Choose I usually tell clients to think honestly about how they actually spend their time, not how they imagine spending it. If you rely on being close to work, school activities, or frequent errands, suburban living is going to serve you better day to day. If you are drawn to space, quiet, and a slower pace, and you are prepared to take on the extra responsibility that comes with rural property, that tradeoff can absolutely be worth it. The buyers who struggle most are usually the ones who choose based on the idea of rural life without testing what the actual logistics look like first. Frequently Asked Questions Is rural land in Minnesota cheaper than suburban land? Land is often more affordable per acre in rural areas, but overall cost of living can even out once you factor in longer commutes and the expense of maintaining wells, septic systems, and larger properties. Do rural Minnesota homes use well water and septic systems? Many rural properties in Minnesota rely on private wells and septic systems rather than city water
What Is It Like Living in Plymouth vs Minnetonka?
Plymouth and Minnetonka both sit in the western suburbs, both have excellent reputations, and both get mentioned in the same breath so often that buyers sometimes assume they are more similar than they actually are, when in practice they serve pretty different kinds of buyers once you dig past the general reputation both cities share. The quick answer: Plymouth is one of the largest suburbs in the metro by land area, offering a wide range of housing and price points across its many neighborhoods, while Minnetonka feels a bit more compact and established, with closer ties to Lake Minnetonka and a reputation for mature, well kept neighborhoods. Both consistently rank among the more desirable addresses in the west metro. Location and Commute Plymouth sits in the northwest metro, with Highway 55 running through the city along with access to I-494 and I-694, giving residents a fairly direct route into downtown Minneapolis or out toward the northwest suburbs. Minnetonka sits a bit farther south and west, closer to Lake Minnetonka, with access to Highway 7, 494, and 394, which tends to work well for commuters heading toward downtown Minneapolis or west toward Wayzata and the lake communities. Housing Stock and Age Plymouth is a large city by land area, and that size shows up in its housing stock, with everything from established neighborhoods built decades ago to newer developments still filling in on the edges of the city. Minnetonka tends to feel a bit more uniformly established, with mature trees, larger lots in a lot of neighborhoods, and a housing stock that reflects steady development over a long period rather than rapid recent growth. Buyers who want the option to choose between an older, more traditional layout and a newer build within the same general area tend to appreciate that Plymouth gives them both without having to leave the city. Schools Plymouth is served by a mix of districts depending on the neighborhood, most commonly Wayzata Public Schools, District 284, along with parts of Robbinsdale and Osseo Area Schools. Minnetonka falls primarily under Minnetonka Public Schools, District 276, one of the more consistently well regarded districts in the state, though some pockets of the city fall into neighboring districts as well. In both cities, confirming the exact district for a specific address matters more than relying on the city name. Shopping, Dining, and Amenities Plymouth has built out a solid retail base along its major corridors, along with community amenities like the Plymouth Creek Center and access to French Regional Park. Minnetonka is home to Ridgedale Center, one of the more established shopping destinations in the west metro, along with a strong arts presence through the Minnetonka Center for the Arts and easy access to the restaurants and marinas around Lake Minnetonka. Residents in both cities also benefit from being close enough to neighboring suburbs that a wider range of shopping and dining is never more than a short drive away, even on the rare occasion a specific store or restaurant is not available locally. Community Feel Plymouth feels spread out and varied given its size, with different neighborhoods carrying somewhat different characters depending on when they were developed. Minnetonka feels more consistently established and a bit more tied to the Lake Minnetonka lifestyle, even in the parts of the city that do not sit directly on the water, with a general reputation for mature, well kept neighborhoods. Buyers often describe Plymouth as feeling like several smaller communities under one city name, while Minnetonka reads as more of a single, cohesive identity from one end of the city to the other. Recreation and Green Space Plymouth has invested significantly in its parks system, with Parkers Lake and French Regional Park giving residents real green space and water access without leaving the city. Minnetonka benefits from its proximity to Lake Minnetonka itself, along with a strong trail system and neighborhood parks, giving residents plenty of outdoor options whether or not they own lake access directly. Both cities also connect into the broader regional trail network that threads through the west metro, so residents in either city can bike or walk well beyond their own neighborhood without ever needing to drive to a trailhead. Price Point Considerations Plymouth’s size works in its favor here, offering a genuinely wide range of price points across its many neighborhoods, which makes it accessible to a broader range of buyers. Minnetonka tends to skew a bit higher on average, particularly in neighborhoods closer to the lake, though pricing still varies enough that comparing specific listings is always the better approach than assuming based on the city name. Employment and Local Economy Plymouth has built out a substantial commercial and light industrial base over the years, giving a meaningful share of residents the option to work close to home rather than commuting into Minneapolis every day. Minnetonka has done the same, with a number of established employers located within the city, which supports a local economy that goes well beyond just being a bedroom community for the core cities. Both suburbs benefit from that local job base, since it tends to support the amenities and services residents rely on daily. Which One Should You Actually Choose If you want a wide range of housing options and price points within one city, Plymouth usually gives you more room to work with. If a more established, lake adjacent lifestyle and consistently mature neighborhoods matter more to you, Minnetonka tends to be the stronger fit. Both cities carry excellent reputations in the west metro, so the decision often comes down to budget and how much you value proximity to the lake itself. Frequently Asked Questions Which suburb is larger, Plymouth or Minnetonka? Plymouth is one of the larger suburbs in the metro by land area, which gives it a wider range of neighborhoods and price points than Minnetonka. Is Minnetonka on Lake Minnetonka? Parts of Minnetonka do border sections of Lake Minnetonka, and the broader city carries a strong connection
What Is It Like Living in Chaska vs Chanhassen?
Chaska and Chanhassen sit right next to each other in Carver County, share a lot of the same general charm, and still trip people up constantly when they are trying to decide which one actually fits their life better, especially once they realize how much the two cities differ once you get past the fact that they are neighbors on a map. The quick answer: Chaska tends to feel like a classic river town with a walkable historic downtown, while Chanhassen leans a bit more spread out and polished, built around standout amenities like the Minnesota Landscape Arboretum and a well known entertainment scene. Both cities sit close enough together that a lot of buyers end up cross shopping them before landing on one. Location and Commute Chaska sits along the Minnesota River in Carver County, connected to the rest of the metro primarily by Highway 212, which has made the commute into the western suburbs and eventually Minneapolis steadily easier over the years. Chanhassen sits just to the north and east of Chaska, also along 212, and tends to feel a little closer to the core of the southwest metro thanks to its proximity to Eden Prairie and the broader 494 corridor. Neither city offers a fast direct shot into downtown Minneapolis, so most residents in both places build their routine around a car and a bit of patience during peak commute hours. Housing Stock and Age Chaska has a genuine historic core near its original downtown, with older homes mixed in among newer developments that have filled in around the edges of the city as it has grown. Chanhassen’s housing stock tends to skew a bit newer and more uniform in a lot of neighborhoods, with larger lot sizes in several areas and a reputation for well kept, spacious properties that draw move up buyers from across the southwest metro. Schools Chaska falls primarily under Eastern Carver County Schools, Independent School District 112, which serves a large stretch of Carver County. Chanhassen is split between that same district and Minnetonka Public Schools, Independent School District 276, depending on the specific neighborhood, so it is worth confirming which district actually serves an address before assuming based on the city name alone. Both districts carry strong reputations across the southwest metro, and families relocating from out of state should plan to tour the actual school their children would attend rather than relying on the city’s overall reputation alone. Shopping, Dining, and Amenities Chaska has built a genuinely walkable downtown with local shops and restaurants that give it more of a small town feel than a lot of suburbs this close to the metro core. Chanhassen is home to some standout regional amenities, including the Minnesota Landscape Arboretum and the Chanhassen Dinner Theatres, along with Paisley Park, which continues to draw visitors from well beyond the southwest metro. Both cities give residents plenty of everyday retail without needing to leave town for groceries or basic errands. Community Feel Chaska reads as a river town that has kept some of its historic character even as it has grown, with a downtown area that actually gets used for community events rather than sitting empty most of the year. Chanhassen feels a bit more spread out and polished, with a community identity built around its parks, its arts and entertainment venues, and a generally well maintained look throughout most of its neighborhoods. Recreation and Green Space Chaska offers residents access to the Minnesota River valley along with the Chaska Community Center, and the city has done solid work connecting its neighborhoods with trails and parks. Chanhassen’s biggest recreational draw is the Minnesota Landscape Arboretum, a genuinely large and well regarded green space that residents and visitors use for walking, seasonal events, and simply enjoying the outdoors. Both cities also sit close enough to Lake Minnetonka and the broader lakes region that boating and lake access are realistic options for residents willing to drive a short distance. Golfers also tend to bring up Hazeltine National Golf Club, which sits in the Chaska area and has hosted major national tournaments over the years, giving the community a bit of extra recognition beyond its own borders. Price Point Considerations Chanhassen tends to skew a bit higher on average given its larger lot sizes and reputation in the southwest metro, though pricing still varies significantly by neighborhood. Chaska generally offers a bit more range, including some of the more established, historic pockets near downtown alongside newer developments on the edges of the city. As always, I tell clients to compare specific listings rather than assuming one city is broadly more affordable than the other, since a well maintained home in an older Chaska neighborhood can sometimes outprice a comparable property in parts of Chanhassen, and the reverse can be true as well depending on lot size and finishes. Employment and Local Economy Chaska has built out a meaningful local employment base over the years, which means some residents can find work close to home rather than commuting into the core cities every day. Chanhassen has done the same, with commercial development along its major corridors supporting a mix of local jobs alongside its residential growth. Neither city functions as a pure bedroom community, and that local job base tends to support the restaurants, shops, and services that make daily life more convenient for residents in both places. Which One Should You Actually Choose If a walkable downtown and a bit of small town character matter to you, Chaska usually wins that comparison. If you want larger lots, a bit more polish, and access to standout amenities like the Arboretum and the Dinner Theatres, Chanhassen tends to be the better fit. Both cities work well for buyers who want space and quiet without giving up easy access to the rest of the southwest metro. Frequently Asked Questions Which city has a more walkable downtown, Chaska or Chanhassen? Chaska has the more walkable, historic downtown of the two, with
What Is It Like Living in Burnsville vs Apple Valley?
Burnsville and Apple Valley end up on the same shortlist so often that I sometimes just start the conversation by asking which one my clients pictured first, because the two cities get confused with each other constantly despite being pretty different once you look closely. The quick answer: Burnsville is the older, more built out of the two, with a well established retail core, river bluff scenery, and a bit more of an urban feel for a south metro suburb, while Apple Valley reads as more spread out and family focused, anchored by the Minnesota Zoo and a growing transit corridor along Cedar Avenue. Both are solid choices, and the differences come down to lifestyle preference more than any clear winner. Location and Commute Burnsville sits along I-35W and I-35E right where the two freeways split, along the Minnesota River in Dakota County, just south of Bloomington and across the river from Eagan. That freeway position makes it one of the more convenient south metro suburbs for commuters heading into Minneapolis, since you are already sitting at a major interchange rather than feeding onto one. Apple Valley sits a bit farther southeast, built around Cedar Avenue, and typically involves a slightly longer drive into the core cities, though the METRO Red Line bus rapid transit line along Cedar Avenue gives residents a real transit option that a lot of south metro suburbs simply do not have. Housing Stock and Age Burnsville developed earlier than Apple Valley in a lot of its neighborhoods, so you will find an older mix of housing mixed in with newer developments near the edges of the city. Split levels and ramblers from the 1960s and 70s sit alongside newer construction closer to the river bluffs and on the city’s outer edges. Apple Valley grew steadily through the 1980s, 90s, and 2000s and tends to have a slightly more uniform, family oriented housing stock from that era, along with newer construction as the city has continued to fill in the land it has left. Buyers looking for a fixer upper or a home with some character often lean toward Burnsville’s older pockets, while those who want a more move in ready feel from a slightly newer build tend to find that more consistently in Apple Valley. Schools Burnsville is served primarily by Burnsville-Eagan-Savage School District 191, while Apple Valley falls mostly under Rosemount-Apple Valley-Eagan School District 196, one of the larger districts in the state. Both districts carry solid reputations across the south metro, and families relocating from out of state should tour the specific schools that would serve their exact address rather than assuming coverage based on the city name, since boundaries in this part of Dakota County can be more layered than people expect. Shopping, Dining, and Amenities Burnsville has one of the more established retail cores in the south metro, anchored by Burnsville Center along with a wide corridor of restaurants and big box stores along County Road 42 and Nicollet Avenue. Apple Valley has its own solid retail presence, but the city is probably best known regionally for the Minnesota Zoo, which draws visitors from across the metro and gives residents a genuinely unique amenity that most suburbs simply cannot claim. Community Feel Burnsville feels a little more layered and established, with bluff top views along the Minnesota River and a downtown feel building around the Heart of the City redevelopment area near the transit station. Apple Valley feels more like a steady, family focused community built around its schools, parks, and the zoo, without quite the same downtown redevelopment energy Burnsville has been pushing in recent years. Recreation and Green Space Burnsville has real topography working in its favor, with bluffs, river views, and Buck Hill giving residents a rare Minnesota option for downhill skiing and snowboarding close to home. Apple Valley leans into its parks and trail system along with the Apple Valley Family Aquatic Center, and of course the Minnesota Zoo sits right in the city, functioning almost like an oversized amenity for residents who end up visiting more often than they expected. Price Point Considerations Both cities offer a genuinely wide range of price points, and neither one reads as broadly more expensive than the other once you start comparing specific neighborhoods. Burnsville’s older housing stock tends to include more entry level options near the center of the city, while Apple Valley’s more uniform development era means less variation from block to block. As always, I tell clients to compare actual listings rather than assuming one city is the cheaper option overall. Getting Around and Daily Errands Both cities lean on a car for most daily life, but each has its own wrinkle worth knowing about. Burnsville’s freeway position means residents can hop on 35W or 35E in almost any direction without much backtracking, which makes errands across the broader south metro fairly painless. Apple Valley’s layout centers more on Cedar Avenue and County Road 42, and the addition of bus rapid transit along that corridor gives commuters heading toward the airport or downtown Minneapolis a real alternative to driving, something that matters more and more to buyers who would rather not add a second car to the household. Which One Should You Actually Choose If freeway access and a bit more topography and downtown energy matter to you, Burnsville usually wins that comparison. If you want a steady, family centered community with a unique amenity like the zoo and a transit option along Cedar Avenue, Apple Valley tends to be the better fit. I usually tell clients to drive both corridors once at rush hour before deciding, because the actual commute experience differs more than it looks on a map. Frequently Asked Questions Which is closer to downtown Minneapolis, Burnsville or Apple Valley? Burnsville generally offers a shorter commute given its position right at the split of I-35W and I-35E. Does Apple Valley have public transit options? Yes, the METRO Red Line bus rapid transit runs